Meet Mike · NMLS #1963693
Mortgage advice should start with your life, not the loan.
Start with the goal. Then build the mortgage around it.
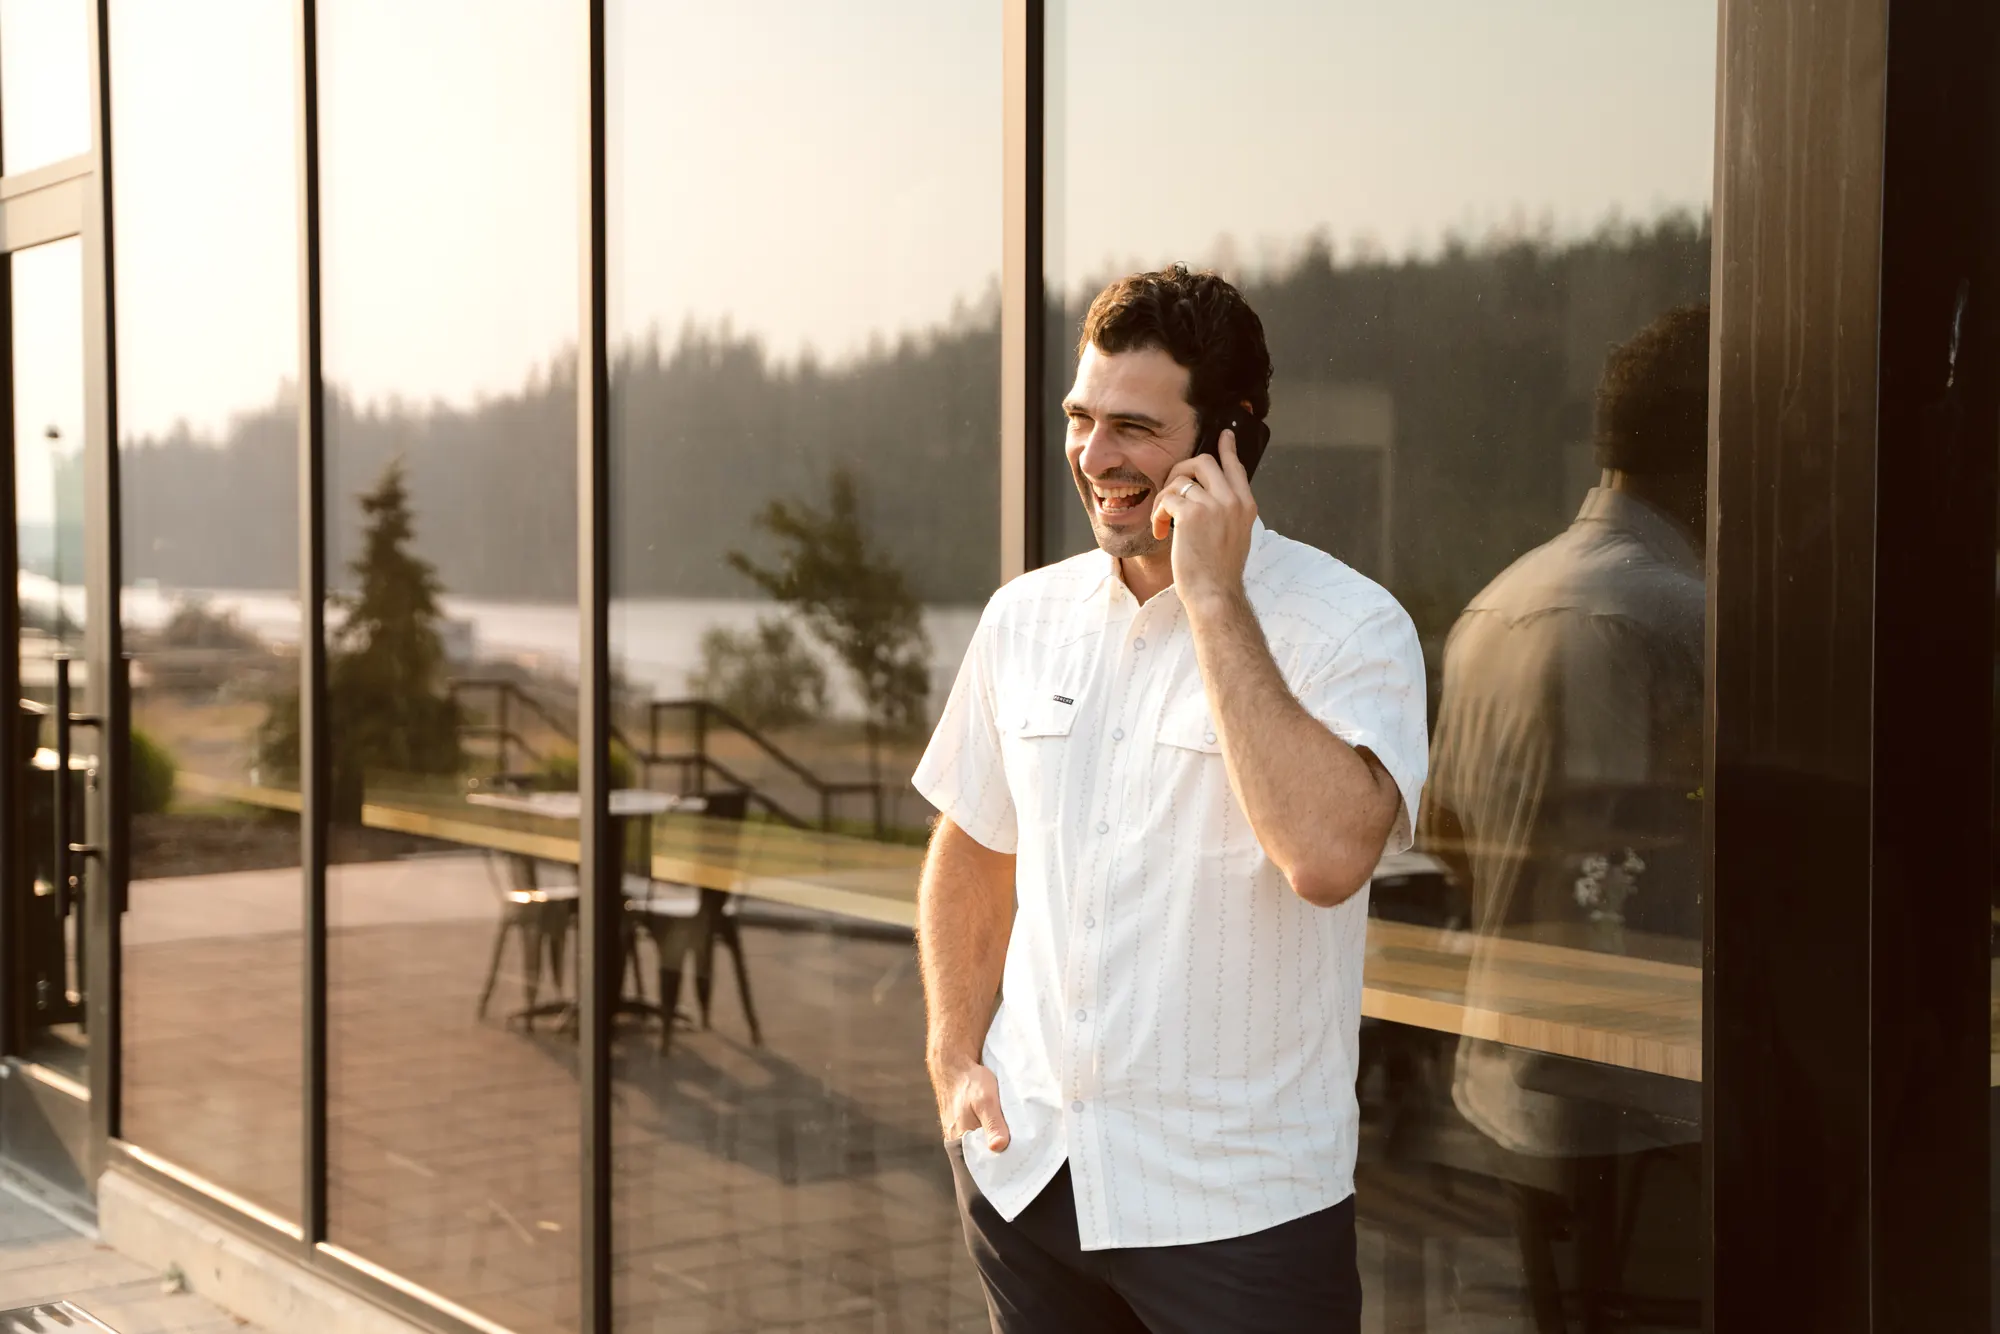
Michael “Mike” Di Lucca
Loan Officer · Canopy Mortgage, LLC
I help families make sense of one of the biggest financial decisions they will make. Before we talk about loan programs or interest rates, I want to understand what you are actually trying to accomplish.
We will talk through the payment that feels comfortable, the cash you want to keep available, your timing, your future plans, and the risks that deserve a backup plan. Once the goal is clear, we can work backward into the mortgage.
Why I do this work
I became a mortgage loan officer because I wanted to help people and families find a home they hope will be their forever home—and provide personal care throughout the homebuying process. My experience in lending, sales, and construction helps me look beyond an approval and explain how the full decision fits together.
Professional record
- Education
- University of Dallas
- Experience
- Lending, sales, and construction
- Individual NMLS
- #1963693 · Consumer Access ↗
- Company
- Canopy Mortgage, LLC · NMLS #1359687
- ID license
- MLO-2081963693
- WA license
- MLO-1963693
How I work
A clear plan before a recommendation
You do not need to know mortgage language or choose a loan program before we talk.
- 01
Understand the goal
We start with your payment, cash, timeline, home plans, and what could change between now and closing.
- 02
Build real scenarios
We compare the numbers behind down payments, reserves, credits, points, and the loan options that may fit.
- 03
Make the tradeoffs clear
You should understand the decision well enough to choose it yourself—not simply agree because a lender recommended it.
Beyond an approval
A pre-approval should make you feel clearer.
An approval is only useful when you also understand the expected payment, cash to close, loan costs, and what the decision leaves available for the rest of your life.
I like using real numbers. If one option costs more up front to lower the payment, we will look at how long it takes to recover that cost. If keeping more cash means a higher payment, we will decide whether that liquidity is worth it to you.
Idaho roots
Family, faith, and personal service
I grew up in Southern Idaho and graduated from the University of Dallas. I am a husband and father, and my Christian faith, lived in the Catholic tradition, is central to how I think about family, service, and responsibility.
Those values shape the kind of mortgage experience I want to provide: personal, careful, and centered on the family making the decision—not just the transaction.
Who I help
Mortgage guidance for real-life situations
- First-time buyers who want to understand the process before writing offers
- Families moving into a larger or longer-term home
- People relocating to North Idaho or Eastern Washington
- Self-employed borrowers working through how their income may be evaluated
- Homeowners deciding whether to sell first or buy first
- Buyers balancing a larger down payment against keeping more in reserves
- Homeowners comparing refinance and home-equity goals
- Buyers comparing Conventional, FHA, VA, USDA, and jumbo options
Available options depend on borrower, property, program, and underwriting requirements.
Where Mike works
North Idaho & Eastern Washington
Start a conversation
Bring your questions. We will build the plan from there.
You do not need to know which loan program you want before we talk.